It’s not unusual for the terms bookkeeping and accounting to be used interchangeably. They are closely connected. But there are also some important differences.
If you run a business, knowing where routine financial administration ends and higher-level accounting begins can help make sure you are getting the right level of support. It can also help you avoid paying for higher-level expertise where it isn’t required and make better use of the finance resource already in your business.
What Is the Difference Between Accounting and Bookkeeping?
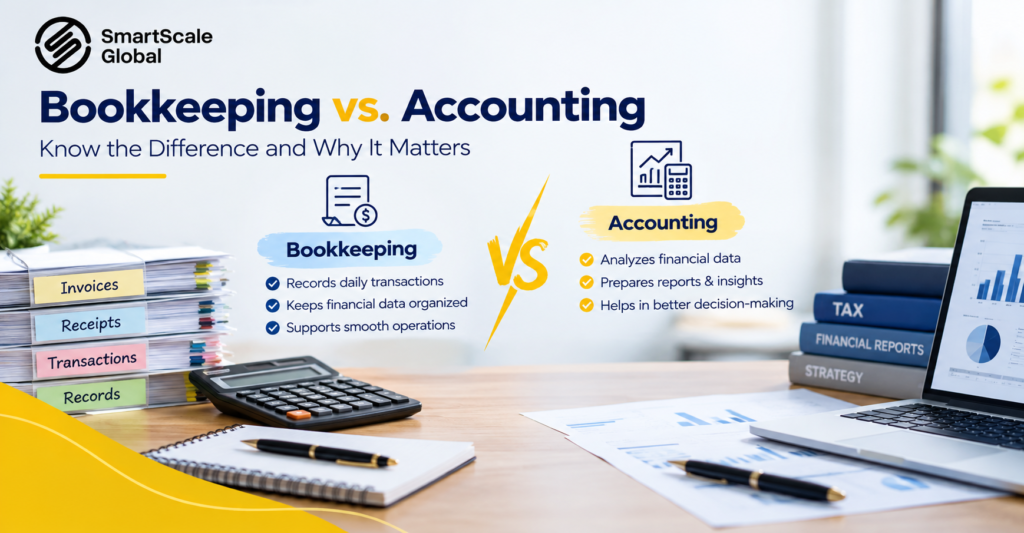
When comparing bookkeeping vs. accounting, both roles are essential in your business, but they serve different purposes.
Think of bookkeeping as the foundation. Your bookkeeper keeps the financial information your business relies on organized and up to date.
Accounting takes those records a step further. Your accountant uses them to prepare reports, meet tax or compliance requirements, support investment decisions, and give you a clearer picture of your financial position.
Here’s an overview:
| Bookkeeping | Accounting |
|---|---|
| Records day-to-day financial activity | Interprets and analyzes financial information |
| Keeps records and accounts current | Uses those records for reporting and decision-making |
| Includes tasks such as invoicing, transaction recording, and reconciliations | Can include financial statements, tax, audit, and planning work |
| Primarily process-led | Requires greater financial analysis and professional judgment |
What Does a Bookkeeper Actually Do?
A bookkeeper’s main job is to keep your day-to-day financial records in order. Depending on your business, this could include recording transactions, reconciling accounts, processing invoices, or keeping expense information current.
These tasks can be high-volume and routine, but their accuracy matters. Missing transactions or records that fall behind can make your financial information less reliable and create delays down the line.
Reliable financial records are essential to the work that follows, which is why bookkeeping and accountancy are so closely linked.
What Does an Accountant Do?
Your accountant will typically use the financial records prepared by your bookkeeper to produce financial statements, review performance, support tax and compliance work, or advise on wider financial decisions.
Some of these accounting activities require professional qualifications or specialist knowledge that routine bookkeeping does not.
While there can be crossover between bookkeeping, accounting, and accountancy, the skills and qualifications needed for routine financial administration are different from those required for analysis, reporting, and professional judgment.
Why Does the Distinction Matter for Your Business?
Understanding the difference between bookkeeping and accounting will help you make sure the right work sits with the right person.
If you have a qualified finance professional spending a lot of time processing invoices or completing routine reconciliations, you may be paying for expertise that the task itself does not require. On the other hand, tax advice, statutory reporting, audit work, and decisions requiring professional accounting judgment need the right level of expertise behind them.
When Should You Consider Outsourcing Bookkeeping?
If you have regular bookkeeping work that needs dedicated attention but not enough to justify another permanent in-house position, outsourcing may be worth considering.
You might notice reconciliations getting pushed back or invoices taking longer to process. Perhaps you or your team are simply spending too much of the working week on routine finance admin when that time is needed elsewhere.
Outsourcing gives you another way to cover that workload without asking your accountant or senior finance team to absorb it.
Read More : How to Choose a Customer Service Outsourcing Partner
What Finance and Bookkeeping Tasks Can Be Outsourced?
A lot of day-to-day finance and bookkeeping work follows defined processes, which makes it well-suited to outsourced support.
SmartScale Global provides outsourced finance administration for tasks including invoicing, reconciliation, and expense tracking. Other suitable tasks may include keeping financial records updated, entering transaction data, or supporting the administrative side of accounts payable and receivable. The scope will depend on your existing systems and the work you need covered.
Tasks, such as tax, audit, or higher-level financial analysis, should stay with your accountant or another suitably qualified finance professional.
What Should You Look for in Outsourced Bookkeeping Support?
Before choosing a provider, look beyond whether they can complete the tasks on your list. Ask how candidates are selected for the work, how they will learn your processes, and how performance will be monitored once the team is in place.
Security matters, too. Anyone working with your financial records may have access to sensitive business information, so you should understand how that data will be accessed and protected.
SmartScale Global builds teams around each client’s requirements, with recruitment, training, and ongoing management included in the service. Its business administration model also includes performance oversight and enterprise-grade data protection.
Build the Right Finance Support Around Your Business
Understanding the difference between accounting and bookkeeping helps you build a finance setup that uses the right level of expertise for each task and avoids unnecessary cost.
Talk to SmartScale Global about where outsourced finance and bookkeeping support could fit into your business.
Get in touch.